Last Updates: 07-June-2026
Home daycare insurance is a special policy that protects people who care for children in their own home. It helps cover costs if a child gets hurt, your property gets damaged, or you face a lawsuit from a parent. Many childcare providers carry this coverage to help protect their business and satisfy state licensing requirements.
Caring for children creates unique liability, property, and business risks that standard homeowners insurance usually does not fully cover. Child injury claims, property damage, and parent lawsuits happen more often in home daycares than in regular homes. Coverage options, costs, and requirements vary by state, insurer, and business structure.
Written by Shumail at Insurenestly
Shumail is an independent insurance researcher and content writer. His goal is to create clear and informational articles that help homeowners understand their options.
Shumail is not a licensed insurance agent and does not provide insurance services or coverage recommendations. He does not sell insurance policies. He only shares research based information so people can make better decisions.
Author Profile: Visit Shumail’s Author Page
What Is Home Daycare Insurance?
Home daycare insurance is a specialized business liability policy designed for individuals who provide childcare services from their homes. It covers financial losses that arise from child injuries, property damage claims, and lawsuits filed by parents none of which are covered under a standard homeowners policy.
Some homeowners policies can be extended with a daycare endorsement, but many typical homeowners policies exclude liability for family daycare activities, and endorsement limits are often too low. This means that if a child is injured in your care and a parent files a lawsuit, your personal assets including your home and savings could be at direct risk without a separate daycare policy in place.
Home daycare insurance vs standard homeowners insurance
| Factor | Home Daycare Insurance | Standard Homeowners Insurance |
|---|---|---|
| Business liability claims | Covered | Excluded in most policies |
| Child injury during daycare hours | Covered | Not covered |
| Abuse and molestation allegations | Available as add on | Not covered |
| Legal defense costs if sued | Included in policy | Not covered |
Why childcare businesses need specialized coverage
- Child injury risks: Playground falls can lead to medical expenses and potential legal costs, depending on the severity of the injury and the circumstances of the incident. A standard homeowners policy does not cover these claims when they arise from daycare business activities.
- Property damage claims: Children breaking furniture, windows, or equipment during care hours is not covered under personal homeowners insurance a separate business policy is required.
- Parent lawsuits:Defending against abuse allegations can involve substantial legal expenses, even when a claim is ultimately dismissed. The total cost depends on the circumstances of the case and the legal proceedings involved. General liability without a specific abuse and molestation endorsement will not cover this.
- Transportation risks: If you transport children, personal auto insurance alone may leave gaps. Ask about a hired and non-owned auto endorsement or a commercial auto policy, and check whether your state or licensing rules require proof of auto coverage.
- Licensing requirements: Roughly 26 states and DC require licensed center-based programs to carry liability insurance, and about 8 states plus DC require family home-based providers to carry coverage. Requirements change as states update regulations, so verify your own state’s current rule with its licensing agency.
What Risks Do Home Daycare Providers Face?
Home daycare providers face real risks every day because they care for children in their own home. These risks can lead to injuries, lawsuits, or expensive repairs, which is exactly why home daycare insurance is so important. Having the right policy helps protect your finances if something goes wrong.
Common incidents that may lead to claims
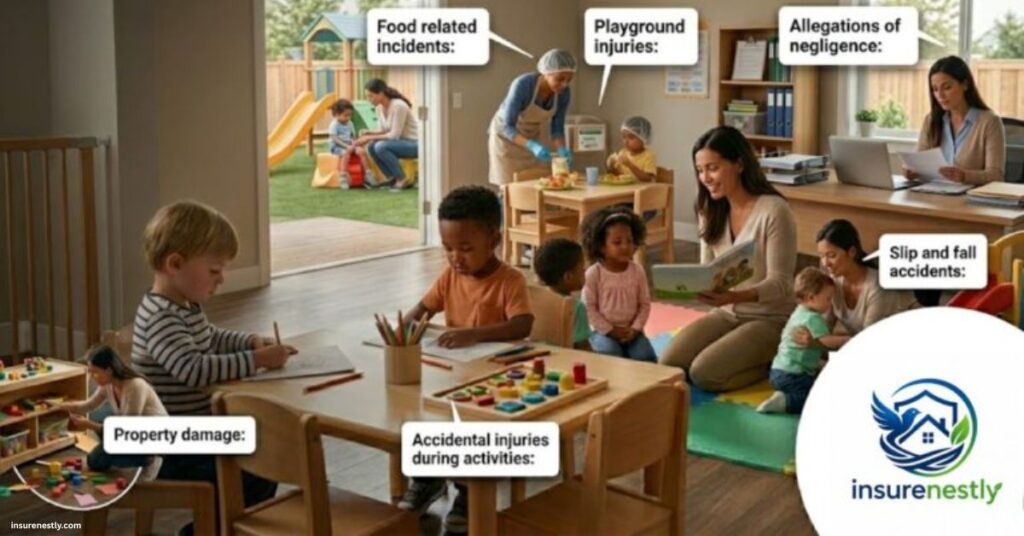
- Slip and fall accidents: Kids can slip on floors or wet surfaces and hurt themselves.
- Playground injuries: Outdoor play areas often have the highest risk of falls or bumps.
- Property damage: A child might break toys, furniture, or windows during play.
- Allegations of negligence: Parents can claim you did not supervise properly or respond to an emergency.
- Food related incidents: Children could get sick from snacks or get hurt while eating.
- Accidental injuries during activities: Common during games, crafts, or group play.
What Does Home Daycare Insurance Typically Cover?
Accident medical coverage pays a child’s medical bills after an accidental injury, often regardless of fault.
Additional coverage options providers may consider
- Abuse and molestation coverage: This coverage pays for your legal defense costs including attorney fees and court expenses and any settlement amounts if a parent files a civil claim alleging abuse or misconduct by you or your staff. Some general liability policies exclude this coverage entirely, so it is important to confirm it is specifically included in your policy before purchasing.
- Commercial auto coverage: Covers your car if you drive children to activities or school.
- Workers’ compensation insurance: Covers employees or caregivers if they get hurt on the job.
- Cyber liability insurance: Protects against data breaches or online issues with parent records.
- Business interruption insurance: Helps cover lost income if your daycare has to close because of a claim.
Who Needs Home Daycare Insurance?
Whether insurance is mandatory depends on your state and license type but even where it isn’t required, a single uninsured claim can reach six figures.
Different types of providers face different levels of risk, so having the right coverage can protect your business and your family. Whether you run a small part time setup or a full time program, insurance helps you handle unexpected situations safely.
Childcare providers who commonly purchase coverage
- Licensed home daycare operators: These providers must have specific insurance to meet state licensing rules.
- Family childcare providers: Many people who care for a few children in their own home get this coverage for personal safety.
- Part time childcare businesses: They usually need basic protection to stay compliant with rules.
- Full time daycare businesses: Larger operations need stronger coverage because of higher activity and bigger risks.
- Preschool operators working from home: They face the same liability concerns as any daycare provider.
- In home child educators: These professionals need protection for both their home and their work.
Part time daycare vs full time daycare operations
| Business Type | Enrolled Children | Key Coverage Needed |
|---|---|---|
| Part time home daycare | 1 – 5 children | General liability, accident medical |
| Full time home daycare | 6 – 20 children | GL, professional liability, abuse and molestation |
| Larger home based program | 20+ children | Full package including auto if transporting |
What Factors Affect Home Daycare Insurance Costs?
Several things decide how much you pay for home daycare insurance. Insurance companies look at your specific situation and the risks involved with your daycare. Knowing these factors helps you understand your quotes and find ways to save money while staying protected.
Key factors insurers evaluate
- Number of children enrolled: More kids usually mean higher risk and higher premiums.
- Business location: Where your daycare is can affect rates because of neighborhood safety or local rules.
- Claims history: Past claims can make insurers see higher risk going forward.
- Years of experience: Longer experience often shows you are more careful and can lower your rates.
- Coverage limits selected: Asking for more protection naturally raises your premium.
- Type of childcare services offered: Different activities (like outdoor play or transportation) change the risk level.
How Much Does Home Daycare Insurance Actually Cost?
According to Fit Small Business, here are the typical annual cost ranges for home daycare insurance coverage:
| Policy | Premium Range per Year | Coverage Amounts |
|---|---|---|
| General Liability In Home Daycare | $500 – $1,500/year | $1 million per claim / $2 million aggregate |
| General Liability Commercial Daycare | $1,100 – $2,200/year | $1 million per claim / $2 million aggregate |
| Commercial Auto | $1,100 – $4,400/year | $300,000 combined single limit for bodily injury and property damage |
| Property Insurance | $550 – $990/year | $15,000 – $20,000 |
| Workers’ Compensation | $5,500 – $7,200/year | $100,000 bodily injury per accident, $500,000 policy limit and $100,000 per employee |
Source to verify: fitsmallbusiness.com
State Insurance Requirements for Home Daycares
Insurance requirements for home daycare providers vary by state. Roughly 26 states and DC require licensed center-based programs to carry liability insurance, and about 8 states plus DC require family home-based providers to hold coverage.
Requirements change as states update regulations, so verify your state’s current rule with its licensing agency. State mandated minimum coverage limits typically range from $100,000 to $300,000 per occurrence, though most insurance professionals recommend choosing limits above the state minimum to protect against larger claims.
Source to verify: revtrak.com
How Can Childcare Providers Reduce Insurance Costs?
Insurers price your premium partly on how you manage risk these steps can lower it.
Practical ways to improve risk management
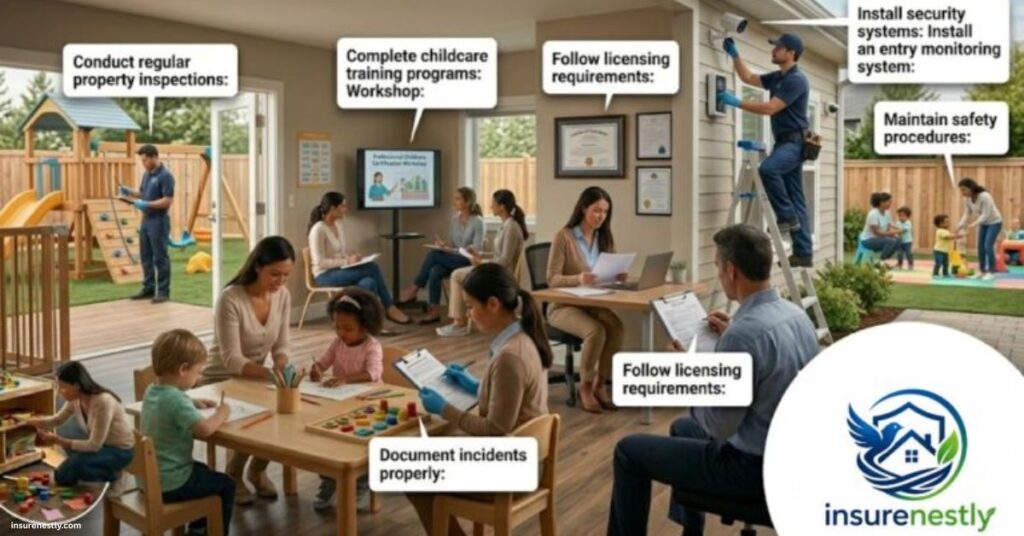
- Maintain safety procedures: Set clear rules for play, snacks, and supervision so accidents stay rare.
- Conduct regular property inspections: Check the home and yard every few months for any hazards.
- Install security systems: Add alarms or cameras to help with safety and documentation.
- Complete childcare training programs: Taking classes on child development and first aid can lower your risk.
- Follow licensing requirements: Meeting all state rules shows insurers you are professional and responsible.
- Document incidents carefully: Keeping detailed records of any events can help support your claim if you need to file one.
Safety improvements that may strengthen insurability
| Safety Measure | What It Involves |
|---|---|
| Childproofing | Cover electrical outlets, secure furniture edges, remove sharp edges |
| Security cameras | Install in entrances, hallways, playgrounds, and common areas |
| Playground maintenance | Daily visual checks for broken equipment, loose bolts, uneven surfaces |
| Emergency preparedness plans | Written fire drill plans, posted exit routes, practiced regularly |
| Staff background checks | Required screening before any adult works with children |
| First aid and CPR training | Certified training for all caregivers |
How Does the Home Daycare Insurance Claims Process Work?
Filing a claim for home daycare insurance is a clear, step by step process. Acting quickly and keeping good records helps the claim move smoothly. Knowing the steps ahead of time makes things less stressful if something happens.
Step by step claims process
| Step | What You Should Do | What the Insurer Does | Typical Timeframe |
|---|---|---|---|
| Incident occurs | Document with photos, written notes, and witness names | — | Immediately |
| Notify insurer | Call your insurer as soon as possible | Opens claim file, assigns adjuster | Within 24 – 72 hours |
| Submit documents | Provide incident report, medical records, parent communications | Reviews documents for completeness | 1 – 5 business days |
| Investigation | Cooperate with adjuster, provide home access if needed | Interviews witnesses, reviews policy coverage | 1 – 4 weeks |
| Settlement decision | Review offer carefully before accepting | Issues written approval or denial | Varies by claim |
Note: This table reflects standard insurance claims procedures followed by most home daycare insurers in the United States. Steps and timeframes may vary depending on your specific insurer and policy terms. For specific claims procedures, contact your insurance company directly or review your policy documents for guidance.
Common reasons claims may be delayed
- Missing documentation: Not sending enough photos, receipts, or reports slows everything down.
- Incomplete incident reports: Vague details force the company to ask for more information.
- Coverage disputes: If there is uncertainty about whether a claim is covered under the policy, the review process may take longer to complete.
- Witness statement reviews: Insurers often need statements from parents or other caregivers.
- Policy exclusion concerns: If something is not included in your policy, the claim takes longer to approve.
Common Insurance Mistakes Home Daycare Owners Should Avoid
Many home daycare owners make simple mistakes that can leave their business exposed or more expensive. Avoiding these mistakes helps keep you protected and reduces the risk of major financial loss if an unexpected event occurs.
Mistakes that may increase financial risk
- Relying only on homeowners insurance: Standard home insurance usually does not cover daycare business risks like child injuries or lawsuits.
- Purchasing insufficient liability limits: Too little coverage means you may not have enough money if a parent sues.
- Ignoring policy exclusions: Missing key exclusions can cause claims to be denied.
- Failing to update coverage as enrollment grows: Keeping old limits when you add more children raises your risk.
- Not documenting incidents properly: Poor records make it harder to handle claims or prove what happened.
Lowest cost policy vs broader protection
| Coverage Type | Minimum You Might See | What Experts Recommend |
|---|---|---|
| General Liability | $100,000 – $300,000 per occurrence | $1,000,000 per occurrence |
| Professional Liability | Often not included in basic plans | $500,000 – $1,000,000 per occurrence |
| Abuse and Molestation | Frequently excluded from cheap policies | $100,000 – $1,000,000, verify it is included |
| Legal Defense Costs | May be capped or subject to sublimits | Fully covered with no sublimit |
| Workers’ Compensation | Sometimes skipped by small operators | Required in most states once you have employees rules and state-fund options vary. |
Source to verify: coveragecriteria.com
Final Thoughts on Home Daycare Insurance
Home daycare insurance helps protect both childcare providers and their businesses from unexpected financial losses. Reviewing your liability limits, exclusions, and coverage options carefully is very important so you always have the right protection. Compare different policies based on the size, services, and risks of your daycare operation. Choosing coverage tailored to your daycare’s size, services, and risks provides real protection and lets you focus on the children with confidence.
Disclaimer
This article is for informational purposes only and is not insurance, legal, or financial advice. Insurance rules and options change by state and company. Talk to a licensed insurance agent for advice specific to your home daycare.
FAQs
How Much Does Home Daycare Insurance Cost?
Home daycare insurance costs vary depending on factors such as coverage limits, the number of children enrolled, business activities, and the insurer. Total costs depend on the number of children enrolled, your location, coverage limits, and whether you add options like abuse and molestation or commercial auto coverage.
What is home daycare coverage?
Home daycare coverage is a business insurance policy designed specifically for childcare providers who operate from their own home. It covers child injuries, property damage, parent lawsuits, and legal defense costs none of which are covered under a standard homeowners insurance policy.
What insurance do daycares need?
Most daycare providers need at minimum general liability insurance. Depending on their operation, they may also need professional liability, abuse and molestation coverage, commercial auto if transporting children, and workers compensation if they have employees.
Does homeowners insurance cover my home daycare?
Usually not fully. Standard homeowners policies exclude business activities, and even daycare endorsements often have low limits. If a child is injured and a parent sues, your homeowners policy alone will likely not cover the legal defense or damages — a separate daycare policy is the safer route.
Can I reduce my home daycare insurance premium?
Yes. Installing security cameras, completing first aid and CPR training, conducting staff background checks, maintaining a clean claims history, and following all state licensing requirements can help lower your premium. Bundling general liability and property coverage into a single business owners policy can also reduce overall costs.

Shumail is an independent insurance researcher and content writer who researches publicly available insurance information and explains coverage, costs, and insurance concepts in simple language. InsureNestly provides educational and informational content only and does not sell insurance or provide insurance advice.
1 thought on “Home Daycare Insurance What Coverage Do Providers Need?”
Pingback: Home Daycare Insurance: A Complete Guide 23