Many homeowners look up the typical home insurance cost when they are buying a house, renewing their policy, or comparing different options. It’s a common question because everyone wants to know what they might have to pay. Getting a clear idea of average costs helps you plan your budget and avoid surprises.
Insurance premiums depend on many things like your property’s characteristics, location, the coverage you choose, and your personal risk factors. No single price fits every homeowner because each insurance company uses its own rating methods.
According to Insurance.com’s 2026 analysis of nationwide rate data, the average cost of home insurance in the U.S. is $2,872 per year, or about $239 per month, for a policy with $300,000 in dwelling coverage, $300,000 in liability protection, and a $1,000 deductible.
Written by Shumail at Insurenestly
Shumail is an insurance content researcher and writer at InsureNestly. His work focuses on translating data from sources like the Insurance.com into clear, accurate guides for everyday homeowners. Shumail is not a licensed insurance agent, broker, or service provider. He does not sell insurance policies or give personalized insurance advice.
Author Profile: Visit Shumail’s Author Page
Why Your Actual Premium Differs From the Average
Home insurance premiums vary among U.S. homeowners based on their individual circumstances. A standard policy usually includes coverage for the home’s structure, liability protection, and a deductible, and national average premiums are typically calculated using these common coverage levels.
Because every research organization collects its own data and applies its own rating methods, published national averages can differ slightly from one another, so it is best to treat them as general reference points rather than fixed prices. In practice, premiums vary dramatically from one state to another — homeowners in areas with fewer natural disasters and lower claim activity often pay far less than the national average, while those in storm-prone or high-litigation regions may pay significantly more.
Your own premium also depends on personal and property factors such as your location, the age and condition of your home, your claims history, and the insurer you choose. For this reason, any published average should serve as a starting point for understanding the market, not as a quote or a guaranteed price.
Typical insurance cost vs actual insurance premium
| Factor | Typical Cost | Actual Premium |
|---|---|---|
| General estimate | Personalized price | Helps you compare options |
| Industry averages | Individual risk profile | Shows what’s common vs your case |
| Accuracy | Broad benchmark | Specific to homeowner |
| Coverage customization | Limited | Fully customized |
The typical cost is useful for planning, but your real premium depends on many personal details.
Which Factors Have the Biggest Impact on Home Insurance Costs?
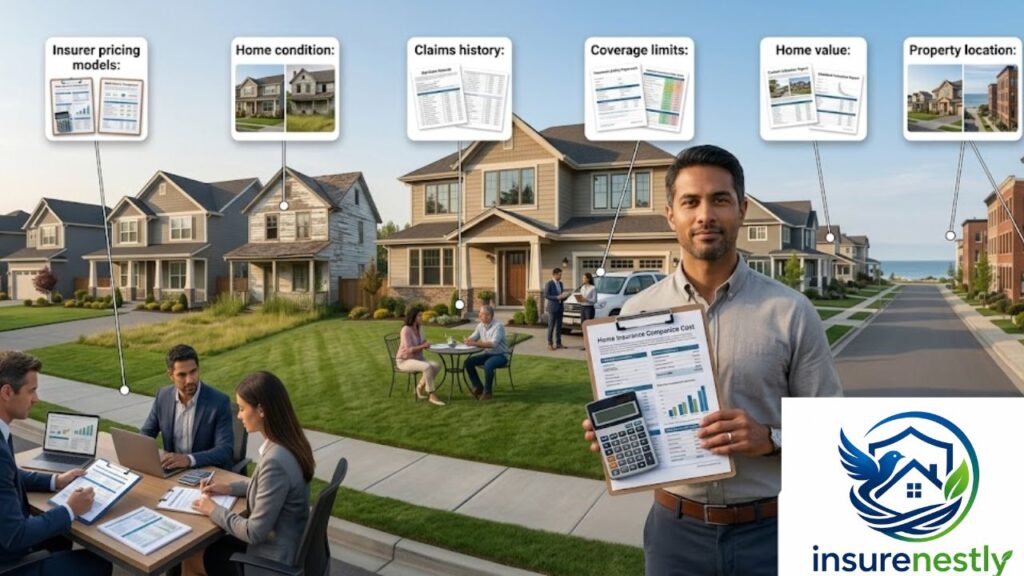
Several things decide how much you pay for home insurance. Insurance companies look at your property and risks closely. Knowing these main factors helps you see why your price might be higher or lower than the average. This gives you a better idea when shopping for coverage.
Property characteristics insurers evaluate
- Age of the Home: Older properties may have higher insurance costs because their systems and components are more likely to experience wear and tear.
- Roof condition: A new or well kept roof can lower your premium. An old roof usually raises it.
- Construction materials: Homes built with strong materials like brick or concrete tend to cost less than those with cheaper ones.
- Square footage: Bigger homes need more coverage, so the price goes up.
- Replacement cost: This is how much it would take to rebuild your home today. Higher rebuild costs mean higher premiums.
- Updated Renovations and Modern Systems: Quality improvements and newer features can help lower your insurance rates.
New construction vs older homes
| Home Age | Typical Premium Trend |
|---|---|
| New construction (0–2 years) | Lowest — modern systems qualify for preferred rates |
| 10-year-old home | Nearly the same as new construction |
| 20-year-old home | Higher premiums may result as home systems age. |
| 30-year-old home | Older home components may lead to higher insurance costs due to potential repair and replacement risks. |
Insuring a newly built home generally costs noticeably less than insuring an older one, even when both carry the same level of dwelling coverage. The main reason is risk newer homes have modern roofing, plumbing, and electrical systems that insurers view as less likely to fail, so these properties often qualify for preferred underwriting rates.
Once a home passes roughly the ten-year mark, premiums tend to climb as these systems age out of those preferred brackets and the likelihood of maintenance-related problems increases. This does not mean older homes are uninsurable, but homeowners should expect rates to rise gradually with the age and condition of the property, making regular upkeep and system updates important factors in keeping insurance costs manageable.
How Location Changes What You Pay
Regional risks that influence premiums
Where your home is located plays a major role in determining your insurance premium. States that face frequent hurricanes, severe storms, or high levels of insurance litigation tend to have the highest average premiums in the country, often far above the national benchmark.
Florida is the most well-known example, where hurricane exposure and a high rate of insurance disputes have pushed costs well beyond what most homeowners pay elsewhere. Louisiana and Kansas also rank among the most expensive states, with both heavily affected by repeated severe storm activity such as hurricanes, tornadoes, and hail. The key takeaway is that location-based risk — not just the value of your home — can be one of the biggest factors shaping what you end up paying for coverage.
On the other end of the spectrum, Hawaii is generally the least expensive state for home insurance, largely because its mild climate limits many common risks — though homeowners there typically need a separate policy for hurricane coverage, which is not included in standard premiums.
Vermont, Delaware, and Alaska also rank among the most affordable states, all benefiting from limited exposure to hurricanes, tornadoes, and wildfires. These states show how lower regional risk translates directly into lower insurance costs, but as with any average, individual premiums still depend on the specific property and homeowner profile.
The gap between the most and least expensive states for home insurance is now measured in the thousands of dollars per year, which means where you live can influence your premium more than almost any other single factor.
Even with identical homes and coverage levels, a homeowner in a high-risk state may pay several times more than one in a low-risk state. This is why national averages should always be read in context — for many homeowners, state-level and even neighborhood-level risk has a bigger impact on cost than the size or value of the property itself.
| Area Type | Real World Example | Average Premium Range |
|---|---|---|
| Highest cost state | Florida (hurricanes + litigation) | Far above the national average |
| Second highest | Louisiana (hurricanes + storms) | Well above the national average |
| Third highest | Kansas (tornadoes + hail) | Significantly above average |
| National average | U.S. overall | Benchmark for comparison |
| Lowest cost state | Hawaii (excludes hurricane coverage) | Far below the national average |
How Coverage Levels Change Home Insurance Costs
More protection means a higher premium, while basic coverage keeps costs lower.
Common coverage types explained
| Coverage Type | Purpose |
|---|---|
| Dwelling coverage | Protects the home’s structure |
| Personal property coverage | Covers belongings |
| Liability protection | Covers legal responsibility |
| Additional living expenses | Covers temporary relocation costs |
These are the main parts of most policies. Higher limits on any of them will usually raise your monthly or yearly cost.
Optional protections that may increase premiums
- Flood insurance: Needed in flood prone areas and often sold separately.
- Earthquake protection: Extra coverage for earthquake damage in risky zones.
- Water backup coverage: Protects against sewer or drain backups.
- Valuable items endorsements: Covers jewelry, art, or other high value belongings.
- Extended replacement cost coverage: Pays more than the basic limit if rebuild costs rise.
Basic coverage vs enhanced protection
| Coverage Level | Typical Cost Trend | Protection Level |
|---|---|---|
| Basic coverage | Lower premium | Essential protection |
| Standard coverage | Moderate premium | Balanced protection |
| Enhanced coverage | Higher premium | Broader protection |
This table shows how stepping up your coverage usually increases the cost. Many homeowners start with standard coverage and add extras as needed.
High deductible vs low deductible
The deductible you choose affects your home insurance costs. It is the amount you must pay yourself before your insurer covers an eligible claim. The exact amount of savings depends on factors like your location, your insurer’s pricing model, and the value of your home, so the impact differs from one homeowner to another.
A deductible in the middle range is commonly treated as the standard starting point for most policies. The practical trade-off to understand is that a higher deductible means paying more yourself if you ever file a claim, while a lower deductible means higher ongoing premiums but less financial strain at claim time. Weighing what you could comfortably afford in an emergency is the key to deciding which direction makes sense for your situation.
| Deductible Option | Typical Premium Effect |
|---|---|
| Lower deductible ($500) | Higher annual premium, but less out-of-pocket cost if you file a claim |
| Standard deductible ($1,000) | The most common baseline; balanced premium and out-of-pocket cost |
| Higher deductible ($2,000) | Lower annual premium, but more out-of-pocket cost if you file a claim |
How Claims History Influences Insurance Rates
Insurance companies see past claims as a sign of possible future risks. A clean record usually helps keep your premiums lower, while multiple claims can push your rates higher.
Why previous claims matter to insurers
Filing a claim signals higher future risk to your insurer and the financial impact is measurable. According to Policygenius, home insurance premiums rise by an average of 7% to 10% after a single claim. Insurers view certain claim types particularly water damage, theft, and liability as especially likely to repeat, often raising rates even after just one such incident.
Beyond one claim, a pattern of filings can affect your ability to get coverage at standard rates. Repeated claims suggest ongoing maintenance issues or property vulnerability that insurers factor heavily into underwriting decisions.
| Claims Profile | Typical Insurance Impact |
|---|---|
| No recent claims | Lower premiums; clean record rewarded |
| One claim filed | 7%–10% average premium increase (Policygenius) |
| Multiple claims | Higher premiums; increased underwriting scrutiny |
| Frequent losses | Possible difficulty securing standard coverage |
How Home Value and Rebuilding Costs Affect Insurance Pricing
Insurers care more about how much it would cost to rebuild your house than what it’s worth on the market today.
Why replacement cost matters more than market value
Insurers set your premium based on what it would cost to rebuild your home today not what it would sell for on the market. This distinction matters more now than ever. Repair and rebuilding expenses have jumped nearly 30% over the past five years, driven by inflation, supply chain disruptions, rising construction material prices, labor shortages, and new federal tariffs.
Even with some moderation, lumber prices remain approximately 20% above their 2019 levels. These ongoing cost pressures mean many homeowners are underinsured their coverage limits haven’t kept pace with what it would actually cost to rebuild after a total loss.
| Home Category | Insurance Implication |
|---|---|
| Lower value homes | Lower rebuild cost = lower dwelling coverage needed |
| Mid range homes | Moderate premiums = verify limits keep up with inflation |
| Luxury or custom homes | High rebuild cost = risk of being significantly underinsured |
| Older homes with outdated systems | Higher rebuild complexity = higher insurer risk |
How Homeowners Can Reduce Insurance Expenses
You don’t have to pay the highest price for home insurance. There are several practical steps you can take to bring your costs down while keeping good protection. Small changes in your habits and home can make a real difference in your premium over time.
Practical ways to lower premiums
- Review Quotes Each Year: Comparing insurance quotes annually can help you discover more competitive rates and potential savings.
- Bundle insurance policies: Combining home and auto insurance with the same company can generate meaningful savings. According to Insurance.com’s 2026 analysis, bundling home and auto insurance saves an average of 15% annually, or about $869 per year. Savings vary by carrier State Farm averages the highest bundle discount at 22%, followed by Farmers at 19% and both Allstate and Nationwide at 17%. Always compare bundled versus separate quotes, since the bundle math only works in your favor when your carrier is competitively priced on both lines.
- Upgrade home security: Adding alarms, cameras, or deadbolts can lower your risk and your premium.
- Improve roof condition: A newer or well maintained roof usually gets you better rates.
- Increase deductibles carefully: Choosing a higher deductible reduces your monthly cost if you can afford it.
- Maintain the property regularly: Keeping your home in good shape shows insurers lower risk.
Home improvements that may improve insurability
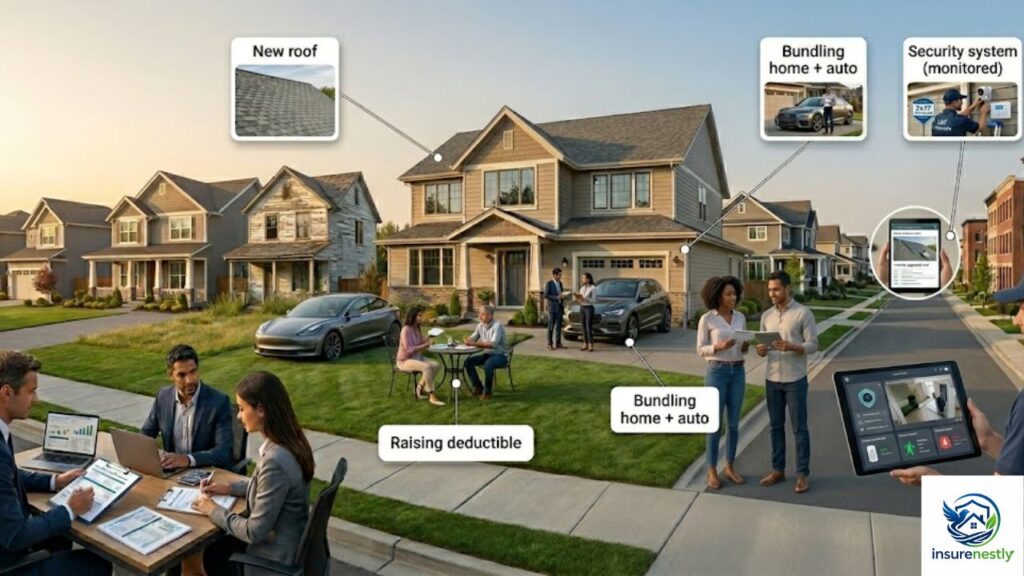
| Home Improvement | Typical Insurance Benefit |
|---|---|
| New roof | Often reduces premiums, as older roofs carry higher claim risk |
| Monitored security system | Commonly earns a discount for lowering theft and damage risk |
| Bundling home + auto | Usually one of the largest available discounts for keeping both policies with one insurer |
| Increasing Your Deductible | Reduces your premium but increases the amount you pay for a claim. |
These upgrades not only protect your home but can also help reduce insurance costs.
Common Misconceptions About Typical Home Insurance Cost
Many people hold wrong ideas about typical home insurance cost. These myths can cause you to overpay or end up with weak protection. Knowing the truth helps you make better choices when buying or renewing your policy.
Insurance myths homeowners should avoid
- All insurers charge similar rates: A common misconception is that all insurers charge roughly the same rates for the same coverage. In reality, insurance companies use their own pricing models, risk assessments, and business strategies, which means quotes for identical coverage can differ dramatically from one insurer to another. Industry analyses of major carriers regularly show gaps of hundreds — sometimes thousands — of dollars per year between the cheapest and most expensive companies for the same home and identical coverage limits. This variation is why comparing quotes from multiple insurers is so important: staying with the first quote you receive, or assuming your current provider offers the best rate, can quietly cost you a substantial amount of money over time.
- Cheapest policy is always the best option: Policies differ in what perils they cover and how claims are paid (replacement cost vs. actual cash value). A cheaper ACV policy pays significantly less on older items after depreciation.
- Flood damage is always included: According to a survey by the Independent Insurance Agents & Brokers of America, 56% of homeowners didn’t know that standard policies don’t cover flood damage. Flood damage is explicitly excluded under standard homeowners and renters policies a separate flood policy must be purchased through the NFIP or a private insurer.
Lowest premium vs balanced coverage strategy
| Lowest Premium Focus | Balanced Coverage Focus |
|---|---|
| Lower monthly cost | Better overall protection |
| Greater coverage gaps | Stronger financial security |
| Higher out of pocket risk | Broader coverage benefits |
This shows why focusing only on the cheapest rate can backfire.
Conclusion
Home insurance pricing depends on many personal and property related factors. Your location, home condition, coverage choices, claims history, and more all play a part. Typical home insurance cost gives you a helpful benchmark, but it cannot predict exactly what you will pay.
The smart approach is to compare policies based on coverage quality, deductibles, exclusions, and overall protection rather than price alone. This helps you get the right balance of cost and security for your home.
Disclaimer
This article is for informational purposes only. It provides general information about typical home insurance costs based on industry averages and common factors. The content is not financial, legal, or insurance advice. Insurance premiums vary widely depending on your specific situation, and no two policies are the same.
We are not licensed insurance agents or advisors. Always consult a qualified insurance professional who can review your property and needs before making any decisions. The information here may change over time, so check with insurance companies for the most current details.
Follow Our Social Accounts:
FAQs
What is a normal home insurance quote?
A normal quote depends largely on your state. National averages offer a general benchmark, but premiums in low-risk states can be a fraction of that figure, while high-risk states can cost several times more for the same coverage. If your quote sits noticeably above your state’s average, gathering quotes from a few additional carriers is a sensible next step.
What makes a home uninsurable?
A home becomes functionally uninsurable when insurers decide the risk is too high for a standard policy showing up as a non renewal, a refusal to issue coverage, or premiums so high they are no longer practical. The most common reasons include location in a high risk flood, wildfire, or hurricane zone; a severely deteriorated roof, foundation, or electrical system; a history of multiple recent claims; and structural damage left unrepaired. In 2026, insurers are increasingly making these decisions at the ZIP code level, with California and Florida homeowners among the most affected as major carriers have exited or restricted coverage in parts of both states.
What does homeowners insurance usually not cover?
Standard homeowners insurance does not cover damage caused by flooding, earthquakes, termites, mold, or normal wear and tear these are the most commonly misunderstood exclusions. Flood damage is explicitly excluded under standard homeowners and renters insurance policies; a separate policy must be purchased through the NFIP or a private insurer. Other standard exclusions include sewer backup, earth movement, government action, and intentional damage all of which require either a separate policy or an endorsement added to your existing coverage to be protected.

Shumail is an independent insurance researcher and content writer who researches publicly available insurance information and explains coverage, costs, and insurance concepts in simple language. InsureNestly provides educational and informational content only and does not sell insurance or provide insurance advice.