Last Updates: 05-June-2026
High risk home insurance is a type of coverage for homes that insurance companies consider more likely to have claims. Some homeowners need this specialized coverage when standard policies are hard to get or too expensive. This often happens because of the home’s age, location, or condition insurers weigh these factors, along with claims history, when setting rates.
Premiums vary dramatically by state in 2024, Florida homeowners paid an average of $14,140, Louisiana $10,964, and Oklahoma $7,762.
Source: Levy Economics Institute of Bard College, April 2026
Written by Shumail at Insurenestly
Shumail is an independent insurance researcher and content writer at InsureNestly. He carefully studies information from different insurance companies, industry reports, and reliable sources to create clear and helpful articles.
Shumail is not an insurance agent or service provider. He does not sell insurance policies. His goal is only to provide straightforward, research based information so homeowners can better understand their options.
Author Profile: Visit Shumail’s Author Page
What Is High Risk Home Insurance?
High risk home insurance is coverage for houses that insurance companies see as more likely to need big repairs or claims. It does not necessarily indicate that your home is poor or low quality. It just means the company thinks there is a higher chance of something going wrong, so they charge more or set stricter rules.
Standard Home Insurance vs High Risk Home Insurance
| Factor | Standard Home Insurance | High-Risk Home Insurance |
|---|---|---|
| Premiums | Generally more predictable | Can be substantially higher in high-risk areas |
| Premium trends | May increase over time | May experience sharper increases |
| Deductibles | Depend on policy terms and coverage | May be higher, particularly for specific risks |
| Coverage availability | Widely available in most states | In 2024, California accounted for 18% of excess and surplus (E&S) direct premiums, while Florida and Texas each represented 16%. |
Source link: NAIC ki 2024 U.S. Surplus Lines Market Share Report
Why insurers classify some properties as high risk
- Older home systems: Outdated electrical wiring, plumbing, or roofs over 15 20 years old increase the chance of fire or water damage.
- Natural disaster exposure: Globally, insured losses from natural disasters reached approximately $140 billion in 2024, making it the third-costliest year for insured losses since 1980, according to Munich Re.
Source link: Munich Re — Natural disaster figures for 2024
- High value homes: High-value homes may require specialized insurance policies when standard coverage does not adequately meet their needs. These policies can offer higher dwelling limits, broader personal property protection, and additional living expense coverage, depending on the insurer and policy terms.
- Poor property maintenance: Yards full of dry brush, broken fences, or visible wear and tear make insurers nervous.
What Makes a Home High Risk?
A home’s location, condition, claims history, and exposure to natural disasters can affect whether insurers are willing to provide coverage. Insurance companies check your property closely and flag anything that could lead to expensive claims. This helps insurers determine your premium rates and coverage options.
Property related factors insurers review
- Roof age and condition: Roofs older than 15–20 years are a major red flag for insurers. Roof damage represents a significant share of residential insurance claims in the United States, contributing to substantial claim costs each year. Roofs in moderate to poor condition have 60% higher claim costs than roofs in good condition. Wind and hail alone drove more than half of all residential roof claims in 2024.
- Wildfire zones: The January 2025 Los Angeles wildfires caused extensive property damage and significant insured losses. In California, the FAIR Plan serves as an insurer of last resort for eligible property owners who cannot obtain coverage through the regular insurance market.
- Plumbing systems: Water damage is a common type of home insurance claim in the United States. The cost of repairs depends on the extent of the damage, its cause, and the coverage provided by the policy. Water damage and freezing account for nearly 28% of all home insurance claims. Most of this damage comes from plumbing failures burst pipes, leaky roofs, overflowed drains rather than storms. Despite this, fewer than 20% of homeowners take any precautionary steps to protect their home against water damage.
- Structural condition: Cracks in foundation, weak supports, or settling issues worry insurers.
- Building materials: Homes with wood shingles or older materials burn faster or hold more damage.
- Property age: Homes built in 1950 or 1980 pay average annual premiums of around $2,505 to $2,514, while homes built in 2024 cost $1,611 to insure over $900 less per year showing just how much age raises risk in insurer calculations.
Source: Home Insurance Statistics 2025
How Location Can Affect High Risk Home Insurance
Your home’s location plays a big role in whether insurers see it as high risk. Some areas have more natural disasters or weather issues, which means higher chances of claims. Companies use maps and past claim data to decide rates for different places.
Geographic risks insurers often consider
- Flood exposure: Flooding is a significant source of property damage in the United States. Even a small amount of floodwater can damage flooring, walls, electrical systems, and personal belongings. Repair costs depend on the severity of the flooding, and standard homeowners insurance generally does not cover flood damage.
- Hurricane prone regions: Coastal states like Florida, Texas, and Louisiana often see expensive wind and storm damage.
- Tornado activity: Tornadoes and severe convective storms can cause widespread property damage across the United States. The resulting losses may include damage to roofs, windows, and structures, while repair costs and insured losses vary depending on the severity and location of each event.
- Coastal property risks: Flood damage can create significant financial losses across the United States, and future risks may increase as flooding patterns change. Flooding can also affect properties outside designated high-risk flood zones, so a property’s location alone may not fully indicate its exposure to flood damage.
Low risk areas vs high risk areas
| Location Type | Actual Average Annual Premium | State Example |
|---|---|---|
| Moderate risk regions | $3,259/year national average 2024 | U.S. average |
| Disaster prone areas | $5,984–$7,762/year | Colorado, Oklahoma |
| Coastal/hurricane locations | $10,964–$14,140/year | Louisiana, Florida |
Source: Levy Economics Institute
Who May Need High Risk Home Insurance?
Some homeowners face more trouble getting normal home insurance. These situations often push them toward high risk policies.
Homeowners commonly seeking high risk coverage
- Property investors: People who own multiple properties may get higher risk labels due to rental use.
- Homeowners with multiple claims: Filing a home insurance claim may affect your future premiums, depending on factors such as the type and frequency of claims, your location, and the insurer’s rating practices. Claims may also appear in a Comprehensive Loss Underwriting Exchange (Comprehensive Loss Underwriting Exchange (CLUE)) report, which insurers can use when evaluating coverage applications.
- High value property owners: Expensive homes with costly features need more expensive coverage.
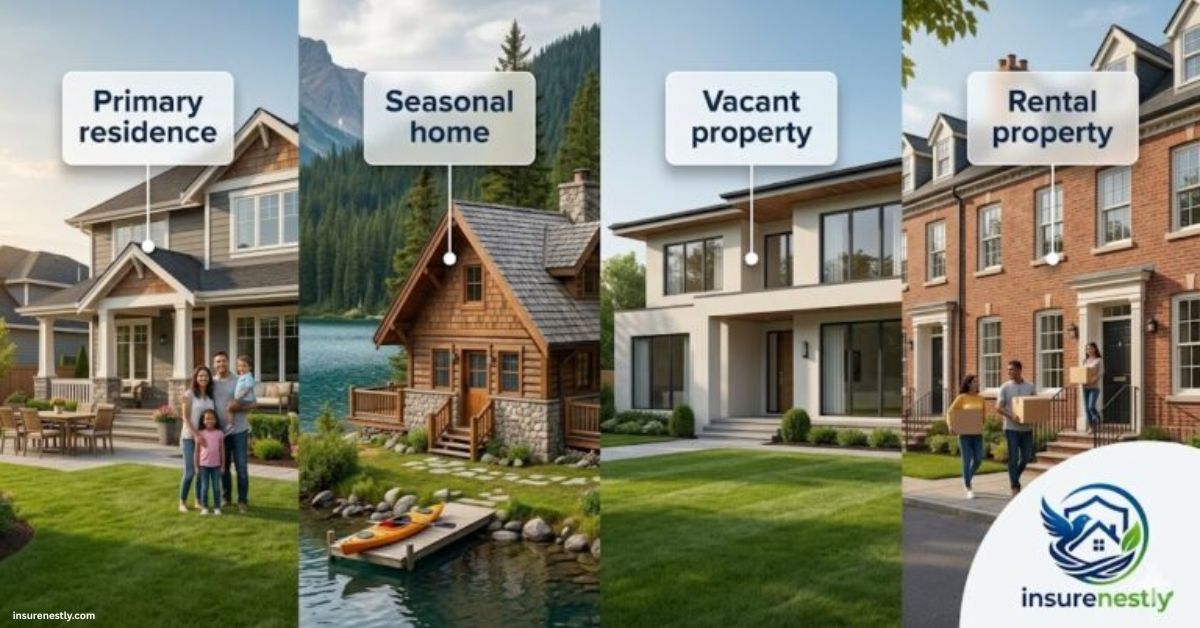
Primary residence vs vacant property insurance needs
| Property Type | Insurance Considerations |
|---|---|
| Primary residence | Standard eligibility may apply |
| Seasonal home | Additional risks may exist |
| Vacant property | Specialized coverage often needed |
| Rental property | Different underwriting requirements |
High Risk Home Insurance Coverage Options
High risk home insurance still gives you basic protection like a standard policy, but it often comes with higher costs and some limits. The exact coverages depend on the insurer and your situation.
Core protections commonly included
| Coverage Type | Purpose |
|---|---|
| Dwelling coverage | Protects the structure |
| Personal property coverage | Covers belongings |
| Liability protection | Covers legal liability risks |
| Additional living expenses | Helps with temporary housing costs |
Optional coverages homeowners may consider
- Earthquake coverage: Important in places with seismic activity as it is not covered by normal policies.
- Sewer backup protection: Covers damage from sewage or drain backups that standard policies often skip.
- Extended replacement cost coverage: Pays more than the basic limit if rebuilding costs rise after a disaster.
- Valuable items endorsements: Adds extra protection for jewelry, art, or expensive belongings.
High Risk Home Insurance Cost Factors
Home insurance premiums depend on factors such as the property’s location, rebuilding cost, coverage limits, deductible, and risk of damage. Insurance companies look at your specific situation and set prices based on the chance of a claim.
What influences insurance premiums?
- Home age: Older homes usually cost more to insure because of outdated systems.
- Claims history: Too many past claims signal higher risk to insurers.
- Property value: Expensive homes or those with costly features need higher coverage limits.
- Coverage limits: Asking for more protection naturally raises the premium.
- Deductible amount: The amount you agree to pay before the insurer steps in affects your rate.
- Geographic location: Living in disaster prone areas pushes premiums up significantly.
Lower risk properties vs higher risk properties
Home insurance premiums vary according to a property’s location, construction, age, claims history, and exposure to natural disasters. Properties facing greater risks of wind or wildfire damage may have higher premiums, although pricing also varies by insurer and coverage selected.
Higher deductible vs lower deductible
| Deductible Choice | Potential Impact |
|---|---|
| Higher deductible | Lower premium |
| Lower deductible | Higher premium |
The average home insurance deductible rose 22% in 2025, up from a 15% increase the year before. Insurers have been raising deductibles, which shifts more of the initial cost of a claim to homeowners. especially in high risk states like Florida and Texas. A higher deductible lowers your monthly premium but means paying significantly more out of pocket when a claim actually occurs.
How Can Homeowners Reduce High Risk Insurance Costs?
You can lower your high risk home insurance costs by making smart changes to your property. Insurance companies often reduce rates when they see fewer risks. Taking action now can help you get better quotes in the future.
Practical ways to improve insurability
- Replace aging roofs: A new roof shows the home is less likely to have leak or storm damage.
- Upgrade electrical systems: Modern wiring reduces the chance of fires.
- Improve plumbing: Updated pipes help avoid costly water damage.
- Add storm protection features: Shutters, reinforced doors, or wind resistant windows help in stormy areas.
- Maintain the property regularly: Clean gutters, trim trees, and fix small issues before they grow.
- Consider AI based home monitoring tools: Insurers are increasingly using AI driven inspections, satellite imagery, and drone assessments to evaluate homes and set premiums based on real time property conditions meaning homes with visible good maintenance now get verified discounts faster than before.
Home improvements that may lower risk
| Improvement | Potential Benefit |
|---|---|
| New roof | Reduced weather related risk |
| Updated wiring | Improved fire safety |
| Security system | Lower theft risk |
| Water leak monitoring | Reduced water damage risk |
How Does the High Risk Home Insurance Claims Process Work?
Filing a claim on a high risk home insurance policy works mostly like a regular policy, but it can take more time because of stricter reviews. Knowing the steps ahead of time helps you stay prepared and avoid common mistakes during a stressful situation.
Step by step claims process
| Step | What Happens |
|---|---|
| Report damage | Contact insurer |
| Document losses | Photos and evidence collected |
| Claim review | Insurer evaluates claim |
| Property inspection | Damage assessment completed |
| Settlement decision | Claim approved or denied |
Common reasons claims may be delayed
2024 U.S. Property Claims Satisfaction Study, the average time from reporting a claim to completing repairs is now 23.9 days more than 6 days longer than what was recorded in 2022. For claims related to catastrophic events like hurricanes or wildfires, that average jumps to 34.2 days. Customer satisfaction with the claims process has dropped to its lowest level in 7 years as a result. Standard claims typically settle within 30–60 days, but complex high risk property claims can take months.
Source: J.D. Power 2024
Common Mistakes Homeowners Should Avoid
Providing incomplete property details, overlooking policy exclusions, or choosing unsuitable coverage can create problems when arranging or using home insurance. Avoiding these errors can save you money and give you better protection in the long run.
Mistakes that can increase insurance costs
- Underinsuring the home: Choosing coverage that is too low to rebuild your house leaves you paying big out of pocket costs after a loss.
- Ignoring maintenance issues: Letting the roof, wiring, or plumbing get worse makes insurers see higher risk.
- Choosing coverage based only on price: The cheapest policy often skips important protections you may need later.
- Failing to update policy information: Not telling your insurer about renovations or changes can cause claim problems.
Cheapest policy vs comprehensive protection
| Cheapest Policy | Comprehensive Protection |
|---|---|
| Lower premium | Broader coverage |
| More coverage gaps | Better financial protection |
| Higher out of pocket risk | Greater peace of mind |
Conclusion
High risk home insurance can help protect properties facing unique challenges like older homes, risky locations, or past claims. It gives homeowners a way to stay covered when standard policies fall short. Make sure you clearly understand your coverage limits, exclusions, and deductibles before buying. Compare multiple policies carefully and review your coverage every year as your property changes. Taking these steps can save you money and give you better peace of mind.
Premiums increased in 95% of U.S. ZIP codes between 2021 and 2024, and in one third of ZIP codes they rose by more than 30%. The sharpest state level increases were in Utah (59%), Illinois (50%), Arizona (48%), and Pennsylvania (44%).
Disclaimer
This article is for informational purposes only and is not insurance, legal, or financial advice. Insurance rules differ by state. Always consult a licensed insurance agent or professional for advice specific to your situation.
FAQs
Why would I be denied homeowners insurance?
Insurers often deny coverage due to a history of multiple claims, very old home systems, poor maintenance, or living in disaster prone areas. High crime locations, vacant properties, or certain dog breeds can also cause denials. They review your claims record, credit, and property condition carefully. Understanding these reasons helps you address the problems and reapply later.
What not to say to home insurance?
Avoid saying anything that is not accurate about your home’s condition, past claims, or changes you made. Do not downplay maintenance issues or hide renovations. Be honest about how the property is used for example, if it is sometimes vacant. Misleading information can lead to denied claims or policy cancellation later. Stick to clear facts when speaking with insurers.
What makes a home harder to insure?
Structural problems like foundation issues, outdated electrical wiring, and aging plumbing devalue a house the most for insurance purposes. An old roof in poor condition also hurts insurability badly. Other big factors include poor overall maintenance and building materials that are not durable. These issues raise risk and often lead to higher premiums or coverage problems.

Shumail is an independent insurance researcher and content writer who researches publicly available insurance information and explains coverage, costs, and insurance concepts in simple language. InsureNestly provides educational and informational content only and does not sell insurance or provide insurance advice.
1 thought on “High Risk Home Insurance Who Needs It and How Does It Work?”
Pingback: Average Home Insurance Cost Complete 2026 Homeowner Guide