Last Updates: 03-June-2026
Drivers in San Antonio often search for car insurance information because of the city’s busy roads, unpredictable weather, and higher risk of vehicle theft. Many want to find affordable coverage that meets Texas state requirements while protecting them from expensive repairs or medical bills after an accident.
This article is for informational purposes only and is not financial or legal advice.Insurance rates in San Antonio can differ widely depending on your driving record, ZIP code, type of vehicle, and level of coverage.Always compare multiple quotes and consult a licensed insurance agent for advice specific to your situation.
Written by Shumail at Insurenestly
Shumail is an independent insurance researcher and writer at InsureNestly. He focuses on researching and explaining auto insurance information for educational purposes. InsureNestly does not provide insurance policies, quotes, or personalized insurance advice. Insurance rate figures are based on the sources cited in each article and may vary by driver, insurer, and coverage details.
Author Profile: Visit Shumail’s Author Page
Why Do Car Insurance San Antonio Rates Differ?
Insurance companies calculate premiums using multiple risk related factors. This is why car insurance rates can vary a lot even within the same city. In San Antonio, where you live, how you drive, and what car you own all play a big role in determining your monthly cost.
Main factors that affect insurance costs in San Antonio
Here are the main factors that affect insurance costs in San Antonio:
- Driver age and experience
- Accident and claims history
- Vehicle repair costs
- Local traffic density
- Annual mileage driven
According to NICB-based reporting, the San Antonio–New Braunfels metropolitan area recorded 12,581 motor vehicle thefts in 2024, down 27% from 17,151 in 2023. These figures refer to the metropolitan area, not San Antonio city alone.
Source: San Antonio Express-News — Car thefts declined in 2024
Urban areas vs suburban areas insurance pricing
| ZIP Code / Area | Neighborhood Name | Rate vs City Avg | Main Reason |
|---|---|---|---|
| These include ZIP codes like 78207, 78201, 78228, 78237, 78210, and 78214. | Inner City areas, including the I-35 and I-10 corridor. | about 10–18% higher than average | Higher claim frequency combined with increased theft rates |
| 78209, 78213, 78229 | Alamo Heights, Castle Hills, Medical Center | Close to city average | Moderate risk zone |
| 78258, 78154, 78023, 78148, 78163 | Stone Oak, Schertz, Helotes, Universal City, Bulverde | 12–20% BELOW average | Lower claim rate + less theft |
| City wide range | All San Antonio | $219/month (liability to full coverage) | Mixed risk profile |
Source: compare.com
What Are Texas Minimum Car Insurance Requirements?
Texas requires every driver to carry at least minimum liability insurance for legal driving. This coverage helps pay for damages or injuries you may cause to others in an accident. State requirements may change over time, so drivers should verify current limits regularly.
Required liability coverage in Texas
| Coverage Requirement | Purpose |
|---|---|
| Bodily injury liability | $30,000 bodily injury coverage per person / $60,000 bodily injury coverage per accident |
| Property damage liability | $25,000 |
Minimum legal coverage vs stronger financial protection
| Coverage Option | Typical Benefit |
|---|---|
| Minimum legal coverage | Lower monthly premium |
| Higher liability limits | Better financial protection |
| Full coverage | Broader vehicle protection |
Meeting the minimum requirements is mandatory to drive legally in Texas. However, many drivers choose stronger coverage for better protection, especially if they have a newer or financed vehicle. It is wise to understand what your policy actually covers.
What Types of Car Insurance Coverage Are Available in San Antonio?
Texas drivers, including those in San Antonio, can choose between minimum legal coverage and broader protection options. The right coverage depends on your vehicle’s value, your budget, and how much risk you want to take. You can start with basic coverage or add more for better security.
Liability insurance vs full coverage insurance
| Coverage Type | What It Usually Covers |
|---|---|
| Liability coverage | Damage and injuries to others |
| Collision coverage | Damage to your own vehicle |
| Comprehensive coverage | Theft, hail, vandalism, fire |
Additional protection options drivers may consider
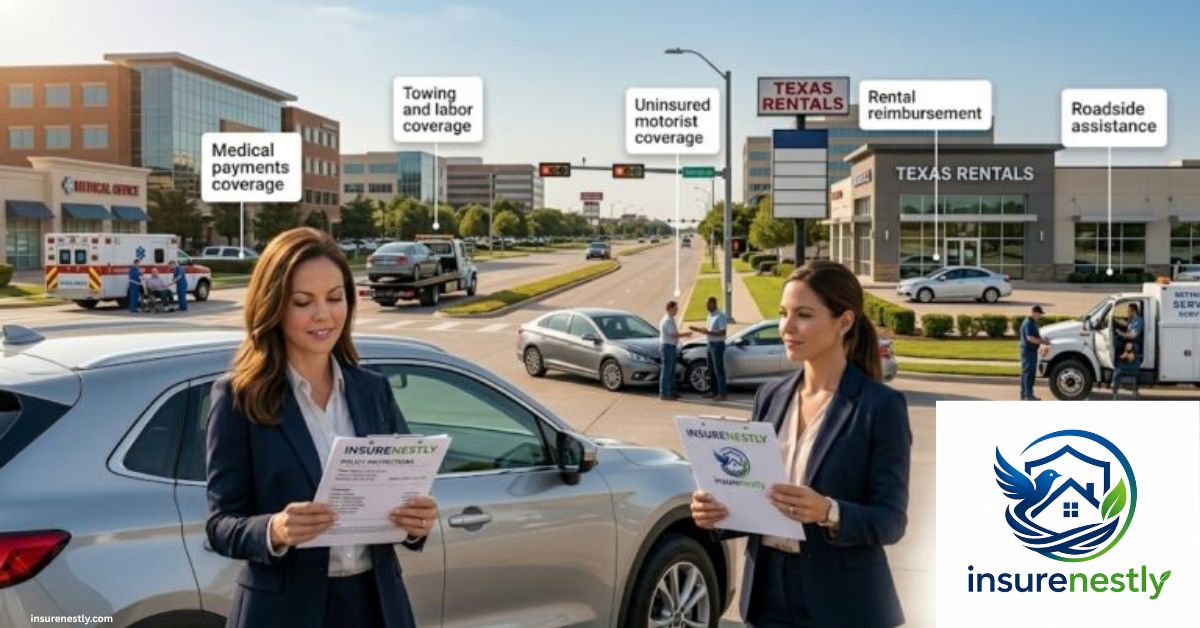
San Antonio drivers may also consider adding these optional coverages:
- Roadside assistance
- Rental reimbursement
- Uninsured motorist coverage
- Medical payments coverage
- Towing and labor coverage
These extra options can provide more peace of mind, especially in a busy city like San Antonio. It’s recommended to contact your insurer to find out what options are available and which ones suit your needs best.
Which Drivers Often Pay More for Car Insurance in San Antonio?
Insurance rates in San Antonio are not the same for everyone. Some drivers pay significantly more due to their age, driving record, and other risk factors. Insurance companies look at these details to decide premiums.
Driver profiles that usually face higher premiums
Here are some driver profiles that often pay more for car insurance in San Antonio:
- Teen drivers
- Drivers with DUI records
- Drivers with multiple accidents
- Luxury or sports car owners
- Drivers with poor credit (where applicable)
Safe drivers vs high risk drivers
| Driver Profile | Typical Insurance Impact |
|---|---|
| Clean driving record | Lower premiums |
| Multiple violations | Higher premiums |
| DUI history | Expensive coverage |
| Experienced drivers | Better pricing opportunities |
Safe drivers with clean records usually enjoy lower rates in San Antonio. High risk drivers, especially teens and those with violations, often face much higher premiums. In San Antonio, teenage drivers pay an average of $272 per month for full coverage, making them one of the most expensive categories to insure.
Source: insuranceopedia.com
How Can San Antonio Drivers Lower Insurance Costs?
Many San Antonio drivers can reduce their insurance costs by making smart choices. Small changes in habits and policy decisions can lead to noticeable savings while keeping proper coverage.
Smart ways to reduce insurance premiums
Here are some effective ways to lower your insurance premiums in San Antonio:
- Compare quotes from multiple insurers
- Maintain a clean driving history
- Increase deductibles carefully
- Bundle insurance policies
- Ask about available discounts
- Avoid unnecessary claims
Common discounts drivers may qualify for
| Discount Type | Typical Requirement |
|---|---|
| Safe driver discount | Clean driving history |
| Multi policy discount | Bundled policies |
| Good student discount | Eligible students |
| Low mileage discount | Reduced yearly driving |
| Defensive driving discount | Approved driving course |
According to NerdWallet’s October 2026 analysis, the average cost of full-coverage car insurance in San Antonio is $3,796 per year. Actual premiums vary by driver, insurer, vehicle, and coverage details.
Source: NerdWallet.com
How Weather and Traffic Conditions Affect Insurance in San Antonio
Local environmental and traffic conditions in San Antonio can influence insurance risk levels. Insurance companies consider these factors when setting premiums because they affect the likelihood of accidents and claims.
Weather related risks that may impact claims
San Antonio consistently ranks among the top metro areas in the United States for hail events, particularly during spring months. The most recent notable hail event occurred on March 31, 2025, with hailstones measuring up to 1.50 inches reported near the city center. The largest hail ever recorded in the San Antonio area reached 4.50 inches in diameter during the historic April 12, 2016 storm.
Source: ApexRoofing
Traffic congestion vs lower traffic areas
| Driving Environment | Insurance Impact |
|---|---|
| Heavy traffic areas | Higher accident risk |
| Moderate traffic zones | Balanced pricing |
| Low traffic areas | Lower insurance risk |
Car Insurance San Antonio rates are currently 19% above the national average, with the city’s average exceeding $3,000 annually compared to the national figure of just over $2,500.
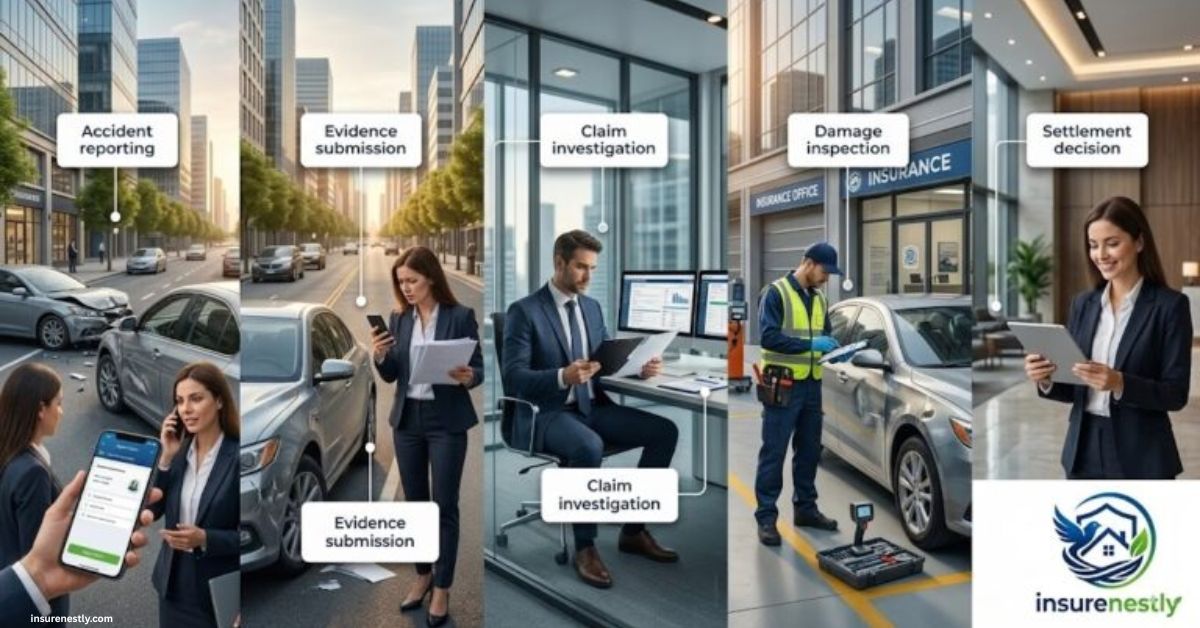
Why some insurance claims face delays
Here are common reasons some insurance claims face delays:
- Missing paperwork
- Incorrect information
- Policy exclusions
- Coverage limitations
- Disputed accident responsibility
Submitting all required documents accurately and on time can help your claim move faster. Always keep records of everything you send to the insurance company.
Conclusion
Drivers should focus on both affordability and financial protection when choosing Car Insurance San Antonio. It is important to compare coverage limits, deductibles, and exclusions carefully before buying a policy.
Balanced insurance decisions may reduce future financial stress after accidents. In San Antonio, car insurance premiums can vary over time depending on insurer rates, driver profiles, and coverage details.
Disclaimer
Car Insurance San Antonio rates, coverage options, and requirements in San Antonio can vary significantly based on your age, driving record, location, vehicle type, credit score, and other personal factors. The information shared here is based on general research and industry averages. Your actual premiums and available coverage options may vary.
InsureNestly and its writers cannot be held responsible for any decisions or financial consequences resulting from this article.
FAQs
Who is cheaper GEICO or Progressive?
Whether GEICO or Progressive is cheaper depends on your personal circumstances, including your driving record, age, credit score, and vehicle type. In many cases, GEICO tends to offer better rates for drivers with clean records, while Progressive may be more competitive for high risk drivers or those who qualify for usage based discounts. The only accurate way to determine which is better for you is to request quotes from both companies using your exact information and carefully compare the full policy details.
What is the three collision rule?
The three collision rule is an educational concept used to explain the physics of a car crash by breaking it into three separate events. The first collision occurs when the vehicle hits another object, the second happens when the occupant’s body strikes the interior of the vehicle, and the third takes place when internal organs collide with the body’s structure. Understanding this principle highlights the importance of wearing seatbelts and having proper safety features, which can reduce injury risk during accidents.

Shumail is an independent insurance researcher and content writer who researches publicly available insurance information and explains coverage, costs, and insurance concepts in simple language. InsureNestly provides educational and informational content only and does not sell insurance or provide insurance advice.