Last updated: 14-May-2026
Full-coverage car insurance in Dallas costs most drivers between $250 and $330 per month in 2026, while minimum liability coverage runs $100 to $150. These costs can vary based on factors such as the driver, vehicle, coverage, and insurer. Below, we cover Dallas rates, Texas coverage requirements, and ways to lower your premium.
Written by Shumail, Founder of InsureNestly
Shumail is the founder of InsureNestly. His work focuses on researching insurance requirements, coverage options, pricing information, and publicly available insurance data for educational purposes.
Why Dallas Drivers Need Car Insurance
Dallas has heavy traffic and a high number of accidents every year. Busy highways and crowded streets make driving risky. Texas law requires every driver to show financial responsibility, and nearly all drivers do that by carrying liability insurance of at least 30/60/25, as explained below. Without insurance, you can face heavy fines, license suspension, or even lawsuits if you cause an accident. Proper coverage protects you your car and other drivers on the road.
What Makes Car Insurance Costs Different in Dallas
Several things affect how much you pay for car insurance in Dallas. The main factors include:
- ZIP code → Some neighborhoods have higher rates due to more accidents and theft.
- Driver age → Younger drivers usually pay more because they are seen as higher risk.
- Vehicle type → Sports cars and expensive models cost more to insure than safe family cars.
- Driving history → Clean record means lower rates. Tickets or accidents can raise your premium quickly.
New and Young Drivers
Age and driving experience can affect car insurance rates. Younger and less experienced drivers may pay more because insurers can consider age and driving history when setting premiums. A new driver can also benefit from maintaining a clean driving record over time.
Tickets, accidents, and other driving violations may affect insurance costs, depending on the insurer and the driver’s circumstances.
New drivers should compare coverage options and ask insurers about any discounts they may qualify for rather than choosing a policy based only on the lowest price.
Types of Car Insurance Coverage Explained
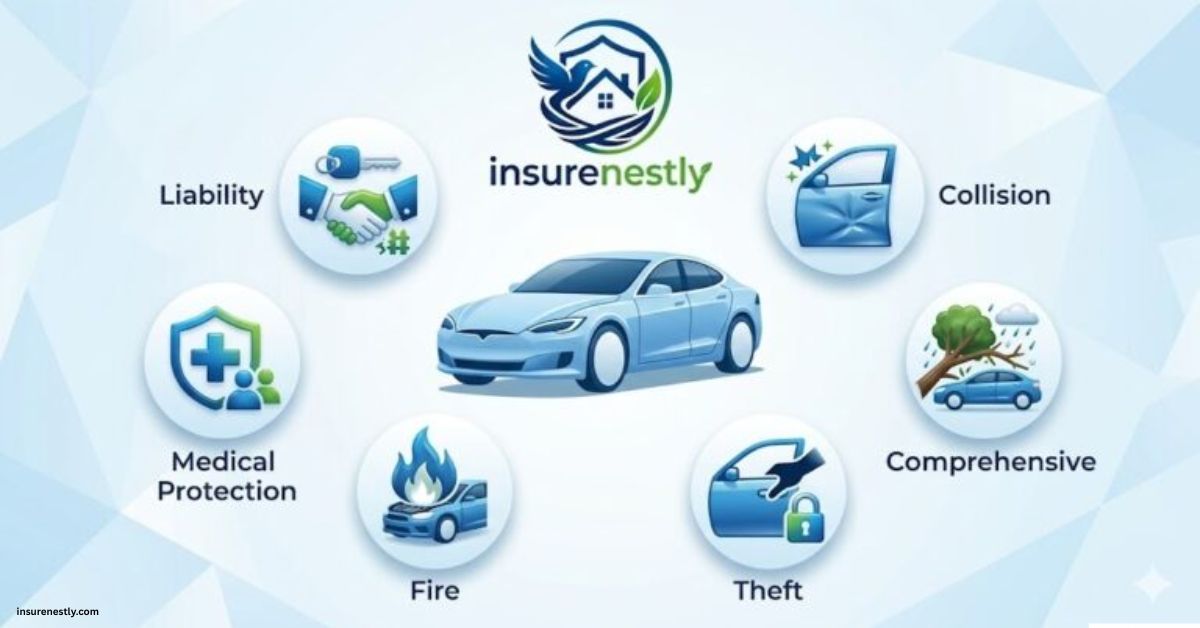
Dallas drivers can choose from several types of car insurance coverage. Knowing these options helps you build a policy that truly protects your car and your wallet in 2026.
Liability Coverage Explained
Liability coverage pays for damages and injuries you cause to other people in an accident. It is the basic coverage required by Texas law. This protection covers the other driver’s medical bills and vehicle repairs but it does not pay for your own car.
Collision Coverage for Vehicle Damage
Collision coverage pays to fix or replace your car after an accident, even if it was your fault. It helps when you hit another vehicle, a pole, or a guardrail.
Comprehensive Coverage for Theft Weather and Vandalism
Comprehensive coverage protects your car from events that are not caused by a collision. It includes:
- Theft
- Hail damage
- Flooding
- Fire
Uninsured and Underinsured Motorist Protection
Uninsured motorist coverage can help pay for covered damages when the at-fault driver does not have insurance. Underinsured motorist coverage can apply when the at-fault driver’s insurance limits are not enough to cover the damages.
These coverages are different from Texas’s minimum liability requirements. They are designed to provide protection in situations where the other driver’s insurance is missing or insufficient, subject to the terms and limits of the policy.
Personal Injury Protection and Medical Payments Coverage
Personal Injury Protection (PIP) can help pay covered medical expenses and certain other costs after an accident, depending on the policy. Medical Payments coverage can help pay covered medical expenses for you and your passengers.
In Texas, insurers must offer PIP and uninsured/underinsured motorist (UM/UIM) coverage with an auto policy. PIP must be offered at a minimum of approximately $2,500, while UM/UIM coverage is generally offered up to the policy’s liability limits. These coverages can be rejected in writing, so check your policy declarations page to see whether they are included or have been rejected.
Average Cost of Car Insurance in Dallas
Car insurance rates in Dallas change a lot depending on your age driving record and the type of coverage you choose. Knowing the average costs in 2026 helps you understand what to expect and where you can save money.
How Much Dallas Drivers Typically Pay
| Driver Type | Avg Monthly Cost |
|---|---|
| Good Driver | $180 |
| Young Driver | $320 |
| Full Coverage | $265 |
Note: Rate estimates in this table are based on publicly available insurance data and are provided for general comparison. Your actual rate may vary depending on your age, driving record, and coverage choice.
Difference Between Minimum and Full Coverage Costs
Minimum coverage is much cheaper than full coverage. Here are the main differences:
- Minimum liability only covers damage you cause to others
- Full coverage includes collision and comprehensive protection for your own car
- Full coverage costs almost double or more than minimum coverage
- Many drivers add full coverage for better peace of mind
Why Prices Vary Between Drivers
Several factors decide how much you pay for car insurance in Dallas:
- Driving record → Clean record means lower rates while accidents or tickets increase the cost
- Car model → Safe and cheaper cars cost less to insure than sports or luxury vehicles
- Location → Some ZIP codes in Dallas have higher rates due to more accidents and theft
Factors That Affect Car Insurance Rates in Dallas
Many things decide how much you pay for car insurance in Dallas. Understanding these factors can help you control your costs and choose better coverage in 2026.
- Age and driving experience
- Driving record and previous claims
- Vehicle type and repair costs
- ZIP code and local traffic conditions
- Annual mileage and daily commute distance
Age and Driving Experience
Young drivers usually pay higher insurance rates because they have less experience on the road. As you get older and build a clean driving history your rates normally start to decrease.
Driving Record and Previous Claims
Your driving record plays a big role in insurance costs. Tickets accidents or past claims can raise your rates significantly. A clean record for several years helps keep your premium low.
Vehicle Type and Repair Costs
The type of car you drive affects your insurance cost. Expensive cars and cars with high repair costs are more expensive to insure. Safer and cheaper to repair vehicles usually come with lower rates.
ZIP Code and Local Traffic Conditions
Where you live in Dallas matters a lot. ZIP codes with heavy traffic more accidents or higher crime rates usually have higher insurance costs. Insurance companies check local conditions carefully before setting your rate.
Annual Mileage and Daily Commute Distance
Drivers who drive more miles every year often pay higher rates. If your daily commute is long insurance companies see you at higher risk of accidents. Driving fewer miles each year can help lower your insurance cost.
Severe Weather and Hail Risk in the Dallas Area
Dallas traffic and weather play a major role in car insurance rates. Busy roads and unpredictable weather increase the risk of accidents and damage. Because of this insurance companies charge higher premiums to drivers in the Dallas area.
High Traffic Congestion and Accident Risk
Heavy traffic raises the chances of accidents every day. Insurance companies know this so they charge higher rates to cover the increased risk of claims in congested areas.
How Dallas Traffic and Weather Impact Insurance Costs
Dallas-area drivers can face weather events that contribute to vehicle damage and insurance claims. The National Weather Service reports that large hail, damaging winds, flooding, and tornadoes affect the Dallas/Fort Worth Metroplex almost every year. For vehicles, comprehensive coverage can help cover certain non-collision damage, including damage from hail, wind, and flooding, subject to the policy terms and deductible.
Weather-related claims are one factor insurers may consider when setting rates. The Texas Department of Insurance explains that the frequency and size of weather events can affect overall claim costs, which can influence insurance premiums.
Source: Dallas/Fort Worth weather information.
Theft and Vehicle Crime in Urban Areas
Vehicle theft and break ins are quite common in several parts of Dallas. Urban areas with higher crime rates see more insurance claims for stolen cars and damaged vehicles. This is one of the main reasons why insurance rates are higher in certain neighborhoods.
How to Choose the Right Car Insurance Policy
Choosing the right car insurance policy in Dallas can save you money while giving you proper protection. Follow these steps to make a smart decision in 2026.
- First understand your daily driving needs and risks
- Compare prices from at least 3 to 4 insurance companies.
- Check customer reviews and claim settlement records
- Make sure the policy fits both your budget and your car
Assessing Your Budget and Coverage Needs
- Figure out how much you can easily afford to pay each month.
- Think about the value of your car and your savings
- Consider how many people usually ride with you
- Check if you park your car in a safe place or on the street
Choosing Deductibles Wisely
A higher deductible lowers your monthly premium but means you pay more out of pocket if you file a claim. A lower deductible costs more every month but gives you less stress during accidents. Choose a deductible you can easily afford when needed.
Deciding Between Minimum and Full Coverage
| Coverage | Best For |
|---|---|
| Minimum | Budget drivers |
| Full | New cars |
Reviewing Optional Add Ons Carefully
- Roadside assistance for breakdowns and towing
- Rental car reimbursement during repairs
- Gap insurance if you have a car loan.
- Personal injury protection for medical costs
Car Insurance Requirements in Texas
Texas law requires every driver in Dallas to have car insurance. Meeting the minimum requirements is mandatory but it is important to understand what these limits actually cover. This section explains the basic rules and why you should know them clearly.
Texas Is an At Fault State
Texas uses an at fault system for auto accidents. When a driver causes an accident, their liability insurance can pay for the other person’s covered injuries and property damage, subject to the policy limits. If the damages exceed those limits, the driver who caused the accident may be responsible for the remaining amount, and the injured person may sue to recover damages.
A person generally cannot recover damages if they are 51% or more responsible for the harm. Because of these rules, Texas’s minimum 30/60/25 liability limits may not provide enough protection in a serious accident.
Texas Minimum Liability Limits (30/60/25) Explained
Texas law requires drivers to show financial responsibility. The minimum liability limits for most drivers are 30/60/25. This means $30,000 for injury to one person, $60,000 per accident, and $25,000 for property damage.
| Coverage Type | Minimum Limit |
| Bodily Injury (Per Person) | $30 000 |
| Bodily Injury (Per Accident) | $60 000 |
| Property Damage | $25 000 |
What Happens If You Drive Without Insurance
A first offense is a Class C misdemeanor with a fine of $175 to $350. Repeat offenses can carry fines of up to $1,000 and may lead to suspension of your driver’s license and vehicle registration. Your vehicle may also be impounded.
Source: tcss.legis.texas.gov
Why Minimum Coverage May Not Be Enough
Minimum coverage might seem cheap but it often falls short in real accidents. Repairing one modern car can easily cost more than $25 000. Medical bills for injuries can go much higher than $30 000 per person. In serious crashes these small limits leave drivers with large out of pocket expenses.
Car Insurance Claims Process in Dallas
If you are involved in a car accident in Dallas, the claims process generally starts with documenting the accident and contacting the appropriate insurance company. Texas follows an at fault system, which means the driver found responsible for causing the accident is generally responsible for the resulting damages, subject to applicable law and the available insurance coverage.
1. Protect Everyone at the Scene and Get Help if Needed
If it is safe to do so, move away from traffic and check if anyone is injured. If anyone needs urgent medical care or emergency assistance, contact 911 right away. In some situations, contacting the police can also provide an official record of what happened.
2. Document the Accident
Take photos of the vehicles, damage, road conditions, and other relevant details if it is safe to do so. Exchange the necessary details with the other driver, including contact and insurance information. If anyone witnessed the accident, record their contact details before leaving the scene.
3. Notify the Insurance Company
Let your insurance provider know about the accident promptly after it occurs. Share the details they ask for and follow their instructions about the claim. They may also tell you which records, documents, or other information you need to provide.
4. Cooperate With the Claims Investigation
The insurance company may review the accident details, inspect vehicle damage, speak with involved parties, and evaluate available evidence before making a coverage or liability decision.
5. Review the Claim Decision
Review the insurer’s decision, including any payment, deductible, coverage limits, or reasons for a denied or limited claim. If you disagree with the handling of a claim, you can ask the insurer for an explanation and learn about complaint options available through the Texas Department of Insurance.
Documents Required for Car Insurance Claims
Here are the main documents you will usually need when filing a car insurance claim in Dallas:
- Driver’s license
- Vehicle registration
- Insurance policy details
- Photos or video evidence
- Police report (if applicable)
Tips to Get Your Claim Approved Faster
Here are some practical tips that can help your car insurance claim in Dallas get approved quicker:
- Provide accurate and honest information
- Report the incident promptly
- Keep proper documentation and evidence
- Understand your policy terms before filing
Following these simple steps can reduce delays and make the process smoother for you.
How to Lower Your Car Insurance Premium
You can reduce your car insurance premium in Dallas without losing important protection. Here are practical ways to save money in 2026:
- Maintain a clean driving record
- Increase deductibles strategically
- Bundle policies for better savings
- Use safe driving and low mileage discounts
- Review your policy every renewal period
Maintain a Clean Driving Record
A clean driving record is one of the best ways to keep your insurance rates low. Avoiding tickets and accidents shows insurance companies that you are a responsible driver. Over time this habit can save you hundreds of dollars every year.
Increase Deductibles Strategically
Raising your deductible can significantly lower your monthly premium. Choose a higher deductible only if you have enough savings to cover it in case of a claim. This approach works well for drivers who rarely file claims.
Bundle Policies for Better Savings
Bundling your car insurance with home or renters insurance often gives you a good discount. Many insurance companies offer lower rates when you buy multiple policies from them. This is one of the easiest ways to cut costs.
Use Safe Driving and Low Mileage Discounts
You can save money through these common discounts:
- Safe driving discount for accident free records
- Low annual mileage discount if you drive less
- Good student discount for young drivers with high grades
- Anti theft device or safety features discount
Review Your Policy Every Renewal Period
Insurance rates and your situation can change every year. Review your policy before renewal to remove unnecessary coverage and find better deals. Shopping around at renewal time often helps you find cheaper options.
Common Mistakes Dallas Drivers Should Avoid
Many Dallas drivers make simple mistakes that end up costing them more money or leaving them under protected. Avoiding these common errors can save you stress and thousands of dollars.
- Buying only the cheapest policy
- Ignoring coverage limits
- Forgetting to update policy information
- Missing renewal dates
- Not comparing coverage options
Buying Only the Cheapest Policy
Buying the cheapest policy is a big mistake many drivers make. Low prices often mean very low coverage limits. When an accident happens you may have to pay large amounts from your own pocket.
Ignoring Coverage Limits
Many drivers never check their coverage limits. They assume the basic policy is enough. In reality medical bills and car repairs can quickly cross these limits and leave you responsible for the extra cost.
Forgetting to Update Policy Information
Life changes like moving to a new ZIP code buying a new car or adding a new driver should be updated in your policy. Forgetting to do so can cause claim problems or higher rates later.
Missing Renewal Dates
Missing your policy renewal date can be dangerous. Your coverage may stop without notice. This leaves you driving without insurance and at risk of heavy fines and license issues.
Not Comparing Coverage Options
Many drivers stick with the same company for years without checking other options. Not comparing coverage and prices means you could be paying more than necessary for the same or even less protection.
Car Insurance Tips for Families
Families in Dallas can save money and stay well protected by smartly managing their car insurance. Here are some useful tips for family drivers:
- Adding multiple drivers to one policy
- Coverage for teen drivers
- Protecting multiple vehicles
Adding Multiple Drivers to One Policy
Adding all family members to a single policy is usually cheaper than buying separate policies. It simplifies payments and often gives better discounts. Always inform your insurance company about every licensed driver in the household.
Coverage for Teen Drivers
Teen drivers are considered high risk so their insurance costs more. Add them to your policy early and ask about good student discounts. Restrict their driving to daytime and limit passengers to help keep rates lower.
Protecting Multiple Vehicles
If your family owns more than one car insuring them on the same policy can bring good multi car discounts. Make sure each vehicle has the right coverage based on its age and value.
When to Review or Change Your Policy
Life changes can affect your car insurance needs and costs. It is important to review your policy at the right time so you stay properly covered and avoid paying more than necessary.
Here’s when you should check your policy:
- After buying a new car
- After moving to a new Dallas ZIP code
- After marriage or family changes
- After accidents or claims history changes
After Buying a New Car
Buying a new or used car is one of the most important times to review your insurance. The new vehicle may need different coverage especially if it is more expensive or financed. Update your policy immediately to avoid driving without proper protection.
After Moving to a New Dallas ZIP Code
Moving to a different ZIP code in Dallas can change your insurance rates. Some areas have higher accident or theft rates. Inform your insurance company about your new address so they can adjust your premium correctly.
After Marriage or Family Changes
Getting married divorced or adding a new family member can affect your policy. These changes may qualify you for discounts or require adding new drivers. Always update your insurance company to keep your coverage accurate.
After Accidents or Claims History Changes
If you have been in an accident or filed a claim your rates may increase at renewal. Review your policy after any claim to understand the impact and explore better options with other companies if needed.
Conclusion
Before choosing or renewing car insurance in Dallas, check that your liability limits meet Texas’s 30/60/25 minimum requirements and consider whether higher limits are appropriate for your situation.
Review your declarations page to see whether PIP and uninsured/underinsured motorist coverage are included or have been rejected. When comparing policies, review the coverage limits, deductibles, and exclusions not just the premium and compare options from multiple insurers.
Disclaimer
The information provided in this guide on Car Insurance in Dallas is intended for general educational and informational purposes only. All cost estimates, average rates, coverage descriptions, and examples are based on publicly available 2026 data from the Texas Department of Insurance (TDI) and reputable research platforms like ValuePenguin. Actual insurance premiums, discounts, and policy terms can vary significantly based on individual circumstances.
This article does not constitute professional insurance, financial, or legal advice. InsureNestly is an independent informational resource and is not an insurance company, licensed insurance broker, or agent. Insurance rules, rates, and regulations change frequently.
Sources & References
- ValuePenguin – Average Car Insurance Rates in Dallas, Texas 2026
- Texas Department of Insurance (TDI) – Car Insurance Rates in Dallas TX 2026
- Texas Department of Insurance — Auto Insurance FAQ
- Texas Transportation Code §601.072 — Minimum Amounts of Financial Responsibility
- Texas Transportation Code §601.191 — Offense and Penalty
- Texas Department of Insurance — Shopping Smart: Tips for Buying Auto and Home Insurance
- Texas Department of Insurance — Auto Insurance Not Renewed or Canceled
- Texas Department of Public Safety — SR-22 Financial Responsibility Insurance Certificate
- National Weather Service — Dallas/Fort Worth Climate Narrative
FAQs
Is full coverage better than minimum liability coverage?
They serve different purposes. Minimum liability coverage helps pay for injuries or property damage you cause to others, while a policy commonly described as full coverage also includes collision and comprehensive coverage for your own vehicle.
Can I get car insurance without a driver’s license?
Insurance requirements and eligibility can vary by insurer and situation. If you do not have a driver’s license, contact an insurer directly to ask whether it can provide coverage and what documentation it requires.
What is an SR-22 in Texas?
An SR-22 is a certificate filed by an insurance company with the Texas Department of Public Safety to show that you are maintaining the required liability insurance. It is not a separate insurance policy. When required, Texas DPS generally requires the SR-22 to be maintained for two years, although a new qualifying conviction or judgment can extend the requirement.
Does Texas require uninsured motorist coverage?
Texas insurers must offer uninsured/underinsured motorist coverage, but the named insured can reject the coverage in writing. Check your policy documents to see whether you have this coverage.

Shumail is an independent insurance researcher and content writer who researches publicly available insurance information and explains coverage, costs, and insurance concepts in simple language. InsureNestly provides educational and informational content only and does not sell insurance or provide insurance advice.
1 thought on “Best Car Insurance in Dallas (2026) How to Compare Policies and Save”
Pingback: No Licence Auto Insurance Costs, Coverage & Legal Guide USA