Last Updates: 09-June-2026
Home insurance costs in the United States vary depending on the home’s location, age, construction, coverage limits, and deductible. Understanding these factors can help homeowners compare policies and make informed coverage decisions. This guide explains the main factors that affect home insurance costs and how homeowners can evaluate their coverage options.
Written by Shumail at Insurenestly
Shumail is an insurance content researcher and writer at InsureNestly. Shumail is not a licensed insurance agent, broker, or financial advisor. All content published under his name on Insurenestly is for educational and informational purposes only. Consult a Licensed Insurance Professional Before Choosing Coverage
Author Profile: Visit Shumail’s Author Page
How Much Does Home Insurance Cost on Average?
Average cost in home insurance means the typical amount most homeowners pay across the country. Insurance companies gather data from thousands of policies to create this figure. It gives you a general idea of what to expect.
What homeowners pay on average in the United States is $2,543 per year, or roughly $212 per month, for a policy with $300,000 in dwelling coverage, $300,000 in liability protection, and a $1,000 deductible, according to Insurance.com’s 2026 analysis.
Why average costs vary among homeowners
Several things cause home insurance prices to go up or down for different people. Here are the main ones:
- Property location: Location is the single biggest driver of home insurance cost. Published home insurance estimates vary by state.
- Home Value and Rebuild Cost: Insurers base premiums on replacement cost the amount needed to rebuild your home today rather than its current market value. Home insurance premiums can be affected by several factors, including rebuilding costs, severe weather losses, reinsurance costs, and insurers’ operating expenses. Home market value and rebuilding cost are not the same: rebuilding cost estimates the expense of reconstructing the home, while market value reflects what the property may sell for. Homeowners should review their dwelling coverage to make sure it reflects the estimated cost to rebuild their home.
- Construction materials: Wood frame homes cost on average 8% more to insure than masonry homes at locations with good fire protection. Homes built entirely of noncombustible materials such as concrete or metal carry the lowest premiums roughly 15% less than masonry.
- Credit-based insurance information (where permitted): In states where its use is allowed, insurers may consider credit-based insurance information when calculating homeowners insurance rates. Rules differ by state, and some states restrict or prohibit its use.
- Claims history: Recent or repeated insurance claims may affect premiums or renewal decisions, depending on the insurer’s underwriting rules and applicable state law.
- Coverage selections: Adding separate flood or earthquake coverage increases your total cost significantly. Flood insurance costs vary depending on the property’s location, flood risk, coverage amount, deductible, and the insurer or program providing the policy. The National Flood Insurance Program (NFIP), administered by FEMA, offers flood insurance to eligible property owners and renters in participating communities. Check current rates and coverage details before estimating the cost for a specific property.
- Insurance company pricing: Rates for the same home can vary by hundreds of dollars across insurers because each company uses its own underwriting formula. Comparing at least three quotes before buying is the most reliable way to find the best rate.
This is for information only and not personalized advice. Insurance needs vary by person. Speak with licensed agents and compare quotes from multiple companies to find what works best for your home.
What Factors Affect the Average Cost of Home Insurance?
Many things decide your insurance premium. Insurers look at your property details, location, and personal situation to set the price. Understanding these factors helps you see why your premium may differ from the national average. Getting quotes from a few companies is the best way to know your real cost.
Property related factors insurers evaluate
Insurers check several parts of your home to measure risk. Here are the main ones:
- Square footage: Larger homes carry higher dwelling coverage limits because they cost more to rebuild. Each additional square foot of living space increases the replacement cost estimate used to set your premium.
- Replacement cost: A study of nearly 5,000 policyholders who filed claims after Colorado’s 2021 Marshall Fire found that 74% were underinsured, while 36% were severely underinsured. These findings relate to people affected by that specific wildfire and should not be interpreted as national estimates for all U.S. homes. United Policyholders, a nonprofit consumer advocacy organization, also reports that its post-disaster surveys have consistently found many homeowners lack enough insurance to rebuild their homes. Insurers calculate premiums based on the estimated rebuild cost, not the sale price of the home.
Source: colorado.edu
- Safety features: Installing monitored alarm systems, smoke detectors, and deadbolts can qualify you for discounts of 5–15% with most major carriers. Storm shutters and impact resistant roofing in hurricane zones can produce further reductions.
- Renovation history: Recent upgrades to electrical panels, plumbing, or the roof demonstrate lower risk to insurers and can improve your rate at renewal. Homes with no documented updates in 20 or more years often face higher premiums or coverage restrictions.
- Roof condition and age: A roof’s age, material, condition, and resistance to weather damage may affect homeowners insurance premiums and coverage eligibility. Some insurers may charge more for older roofs, limit roof-damage coverage, or decline to renew a policy, depending on the roof’s condition and the insurer’s underwriting rules. Homeowners should review their policy to understand how roof damage is covered and whether replacement-cost or actual-cash-value terms apply.
Newer homes vs older homes insurance costs
Home age plays a big role in determining your home insurance premium. Owners of homes built in 1950 and those built in 1980 pay very similar amounts, with average annual premiums of $2,505 and $2,514 respectively.
However, newer homes built in 2024 are much cheaper to insure. The average annual premium for a a home built in 2024 is $1,611 which is over $900 less than homes from 1980 and $1,316 below the national average.
| Home Build Year | Average Annual Premium |
|---|---|
| Built in 2024 (new) | $1,611/year |
| Built in 1980 | $2,514/year |
| Built in 1950 | $2,505/year |
SOURCE: ulw.guardianservice.com
How Location Influences Home Insurance Rates
Your home’s location plays a big role in determining home insurance costs. Insurers study local risks and past claims in your area to set premiums. A house in a safe, calm place usually costs less to insure than one in a high risk zone. This is one reason why typical home insurance costs varies so much from one homeowner to another.
Geographic risks that affect premiums
Insurers pay close attention to natural and man made risks in your area. Common factors include:
- Hurricanes: Coastal homes in hurricane zones often face much higher premiums.
- Tornadoes: Areas in Tornado Alley see increased rates due to frequent wind damage.
- Wildfires: Regions with dry forests and high fire risk, like parts of California, pay more.
- Flood exposure: Homes near rivers, coasts, or low lying areas usually need separate flood insurance.
- Severe storms: Frequent hail, wind, or ice storms raise the chance of claims and costs.
- Crime rates: Neighborhoods with higher theft or vandalism often have elevated premiums.
Low risk areas vs high risk areas
Where a home is located can affect insurance pricing because weather risks, local rebuilding costs, and other property-related factors vary by area. Homeowners insurance rates vary significantly from state to state, with Florida homeowners facing the highest rates in the nation at $8,471 on average annually, while Hawaii sees the lowest at $738 per year.
SOURCE: Insurance.com
How Coverage Choices Impact Home Insurance Costs
The type and amount of coverage you choose directly affects what you may pay for coverage. Basic policies cover standard risks, but adding more protection raises the price. Knowing these options helps you balance good coverage with affordable premiums while protecting what matters most to you.
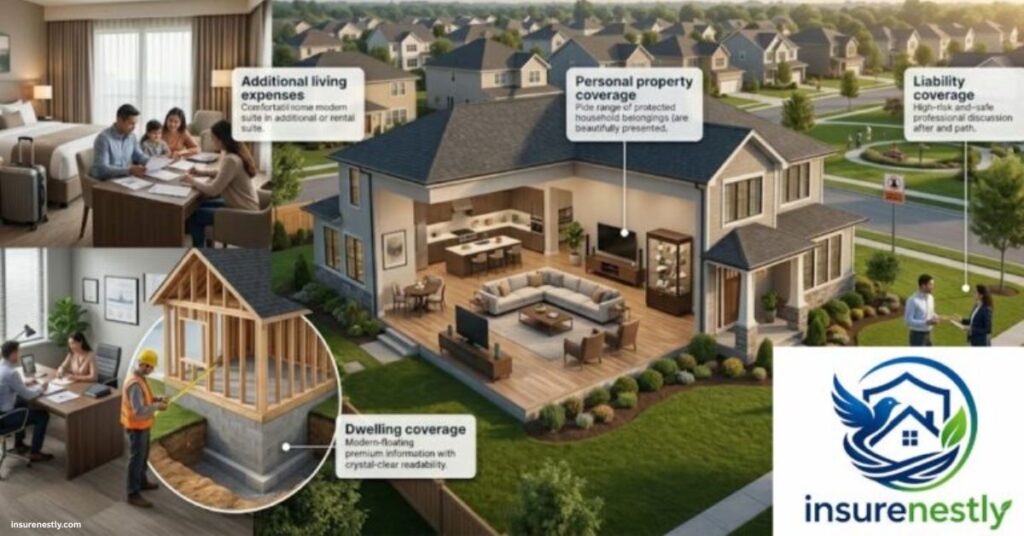
Common home insurance coverages explained
| Coverage Type | Purpose |
|---|---|
| Dwelling coverage | Protects the structure |
| Personal property coverage | Covers belongings |
| Liability coverage | Covers legal responsibility |
| Additional living expenses | Covers temporary housing costs |
Optional coverages that may increase premiums
Here are some common add ons that can raise your costs:
- Flood insurance: Standard home insurance policies never cover flood damage. The average FEMA flood insurance policy costs $75 per month.
- Earthquake coverage: Earthquake damage is excluded from standard policies. Earthquake coverage must be purchased as a separate policy or endorsement, since standard home insurance excludes it. Costs vary widely based on your location, home value, and construction type. Homeowners in high-risk states such as California should get quotes from multiple insurers, as premiums in seismic zones can run substantially higher than the national norm.
- Water backup protection: Covers damage from sewer or drain backups.
- Scheduled valuables coverage: Provides extra protection for jewelry, art, or expensive items.
- Extended replacement cost protection: Pays more than the basic limit if rebuild costs rise.
How Claims History Affects Insurance Costs
Your claims history plays a major role in your annual insurance costs. Insurance companies check past claims to judge how likely you are to file new ones. A clean record usually helps keep costs down, while several claims can push your premium higher. This is one of the most important factors influencing your final insurance premium.
Why insurers review previous claims
Insurers look at your claims record for these main reasons:
- Risk assessment: They use it to measure the overall risk your property carries.
- Frequency of losses: Multiple claims suggest higher chances of future losses.
- Property maintenance concerns: Frequent claims may point to poor upkeep of the home.
- Future claim probability: Past patterns help predict what might happen next.
- Underwriting decisions: This information helps them decide whether to offer coverage and at what price.
No claims history vs multiple claims history
Your claims record follows you through a standardized database called a CLUE report (Comprehensive Loss Underwriting Exchange). Insurance carriers can access a property’s claims history through the CLUE report, which tracks claims for as long as seven years after submission. Typically, fewer claims correspond to a lower risk in the eyes of most home insurance providers.
| Claims Profile | Likely Impact on Premium |
|---|---|
| No claims in 7 years | Eligible for claims free discount |
| One recent claim | Moderate premium increase; discount lost |
| Multiple claims | Higher premium; possible non renewal risk |
| Frequent claims | Insurer may decline renewal or deny coverage |
How Homeowners Can Lower Insurance Costs
You don’t have to pay the highest price for home insurance. Many homeowners cut their premiums by taking simple steps and making smart choices. Small changes in your habits and property can make a real difference in what you pay each year. Start by reviewing your policy and exploring ways to reduce risk.
Home Insurance Discounts to Explore
- Bundling: Some insurers offer a discount when you purchase home and auto insurance together.
- Security features: Eligible alarm systems, smoke detectors, and other protective devices may qualify for discounts.
- Higher deductibles: Choosing a higher deductible may lower your premium, but it also increases the amount you pay out of pocket for a covered claim.
- Roof replacement: A new roof may affect eligibility or pricing, depending on its materials, condition, and the insurer’s rules.
- Impact-resistant materials: Some insurers offer incentives for qualifying roofing materials designed to resist hail or other weather damage.
Discounts and eligibility vary by insurer and state. Ask your insurer which savings apply to your property and confirm the terms before making changes.
Home improvements that may improve insurability
| Home Improvement | Typical Premium Discount |
|---|---|
| New roof (standard asphalt) | 5–35% reduction; national average around 20% |
| New roof (impact resistant Class 4 shingles) | Up to 40% in hail prone states like Colorado |
| Home security system (monitored) | 5–15% depending on insurer and system type |
| Updated electrical panel | Removes fire risk surcharge; may restore eligibility for coverage |
| Plumbing upgrades (copper or PEX) | Reduces water damage risk; lowers renewal premium in older homes |
Common Mistakes When Estimating Home Insurance Costs
Many homeowners get surprised by their actual insurance bill because they make wrong assumptions when estimating costs. Relying on rough guesses instead of real details can lead to underinsurance or overpaying. Understanding common mistakes helps you set realistic expectations and make better decisions for your home insurance.
Mistakes that may lead to inaccurate expectations
Here are some frequent errors people make:
- Focusing only on national averages: The national average of $2,543 per year applies to a standard $300,000 dwelling policy with a $1,000 deductible. Your actual rate depends on your specific state, ZIP code, home age, roof condition, and claims history all of which can shift the number significantly in either direction.
- Ignoring local risk factors: The Insurance Information Institute’s 2022 data identified wind and hail, water damage and freezing, and fire and lightning as major sources of homeowners insurance losses. These figures describe the share of losses incurred, not the percentage of all claims filed. Homeowners in storm corridors or flood prone areas who do not account for local risk often end up with coverage gaps that only become visible after a loss.
- Underestimating replacement costs: A 2025 University of Colorado Boulder study analyzed nearly 5,000 insurance claims from the 2021 Marshall Fire in Colorado. The study found that 74% of policyholders were underinsured, while 36% were severely underinsured, meaning their coverage was less than 75% of the estimated cost to rebuild their homes. Using market value instead of rebuild cost is the leading cause of this problem.
- Choosing insufficient coverage: The cheapest policy usually carries the lowest dwelling coverage limit which may not be enough to fully rebuild after a major loss.
- Overlooking policy exclusions: Standard homeowners insurance policies generally exclude flood and earthquake damage. Additional policies or endorsements may be necessary for these risks, depending on the insurer and coverage terms. These require separate policies. Many homeowners are not aware that home insurance does not cover floods or earthquakes until after a claim is denied.
Conclusion
National home insurance averages can help you understand general cost trends, but they do not determine how much coverage your property needs. The key is to choose dwelling coverage that reflects your home’s estimated rebuilding cost, not just its market value, and compare at least three quotes using similar coverage limits and deductibles.
Disclaimer
This article is for educational and informational purposes only. Average homeowners insurance premiums and all details mentioned here are general estimates based on publicly available data and industry trends in 2026. Actual premiums can vary widely depending on your specific home, location, coverage needs, and other personal factors.
Data and Methodology Note: Home insurance cost figures are based on the sources linked in this article, including Insurance.com, Insurify, and relevant official or research publications. Estimates may use different coverage limits, deductibles, and calculation methods, so they may not be directly comparable. State-level rates and individual premiums can vary.
FAQs
How much should homeowners insurance cost on a $600,000 house?
The price of insuring a home for $600,000 depends on its location, construction, deductible, and selected coverage. Check current estimates from a reliable source and compare them using the same coverage assumptions before relying on a specific annual premium.
Is an older house more expensive to insure?
Yes, older homes generally cost more to insure than newer ones, and the data shows a clear pattern. Home insurance rates are not based on market value but on what it costs to rebuild the home and older homes often have outdated electrical panels, aging plumbing, and roofs that are more likely to generate claims. Homes built in 1950 and 1980 carry average annual premiums of around $2,505 and $2,514 respectively, while a home built in 2024 averages just $1,611 per year over $900 less. Additionally, insurers have become stricter about roof age in recent years, and some carriers will not renew policies on roofs older than 20 years, which further raises costs for older home owners.

Shumail is an independent insurance researcher and content writer who researches publicly available insurance information and explains coverage, costs, and insurance concepts in simple language. InsureNestly provides educational and informational content only and does not sell insurance or provide insurance advice.
1 thought on “Average Cost of Home Insurance in 2026 Rates by State and Home Value”
Pingback: Vacant House Insurance Cost, Coverage & Complete Guide